The Wealth Concentration Reality in Your Neighborhood
Walk through any American suburb today and the numbers behind economic inequality take on concrete form. The modest ranch house where a teacher raised three children now sells for twice what a similar educator could afford. The corner coffee shop that once employed high school students at decent wages has been replaced by an app-driven delivery hub where drivers earn unpredictable gig payments. These local changes reflect a broader transformation: across developed nations, the wealthiest one percent now controls more assets than the bottom sixty percent of households combined.
This concentration shows up differently in each community, but the patterns stay the same. In suburban Phoenix, young families delay buying homes while their parents’ property values soar beyond reach. In rural Ohio, family farms face pressure to sell to agribusiness conglomerates as operating costs outpace what small-scale operations can bring in. Urban neighborhoods from Portland to Birmingham watch longtime residents get pushed out by investors who buy up multiple properties to park their money. The Inequality.org data shows how these local experiences connect to national trends that are rewriting the fundamental bargain of American economic life.
Housing Costs Squeeze Local Families
Housing expenses now eat up a bigger chunk of household budgets than we’ve seen in four decades across English-speaking countries. For American families, this means mortgage payments and rent that would have been luxury spending for previous generations now count as basic survival costs. A firefighter in Austin finds that the modest home her parents bought on a single income now requires two professional salaries to afford. A construction worker in Denver discovers that the apartment he rented as a young adult now costs more than his current mortgage payment would be, if he could even qualify for one.
Local governments face impossible choices as housing costs spiral beyond middle-class reach. Zoning decisions that once balanced neighborhood character with growth now determine which families can stay in communities where they work. Teachers, police officers, and city employees increasingly commute from distant suburbs, creating staffing problems for basic services. Small businesses struggle to attract workers who can’t afford to live nearby, while service industry employees patch together multiple gig jobs to cover rent that eats sixty or seventy percent of their income.
These housing pressures create ripple effects throughout local economies. School districts lose enrollment as families move to cheaper areas, cutting per-pupil funding. Local retailers face declining foot traffic as residents spend their extra money on housing costs rather than community businesses. City tax bases stagnate when productive workers relocate to areas where housing stays affordable, leaving behind either very wealthy residents or very poor ones. Neither group generates the middle-income tax revenue that funds parks, libraries, and keeping the roads fixed.
The Gig Economy’s Local Impact
The job market in communities across America increasingly revolves around platform work that offers flexibility at the cost of traditional job security. Uber and Lyft drivers navigate your local streets, DoorDash couriers deliver to your neighbors, and TaskRabbit workers assemble furniture in nearby homes. This gig economy expansion reflects broader labor market changes, but regulatory battles from California to the European Union show that communities can shape how these new work arrangements actually function.
California’s AB5 legislation tried to reclassify many gig workers as employees, triggering massive corporate spending to overturn the measure through Proposition 22. Similar regulatory discussions play out across Australia and throughout European Union member states, where policymakers wrestle with balancing worker protections against platform innovation. These decisions directly affect local workers who increasingly depend on gig income to supplement traditional jobs or replace work that disappeared during economic transitions.
Local communities see the practical consequences of gig economy growth in their daily routines. Restaurant workers pick up delivery shifts to cover rent increases. Retired teachers drive for ride-sharing companies to supplement inadequate pensions. College students provide freelance services through platforms that offer immediate income but no benefits or long-term career development. The spread of these arrangements reflects both increased economic pressure on households and the failure of traditional employment to provide enough income security for middle-class life.
Policy Responses Take Shape
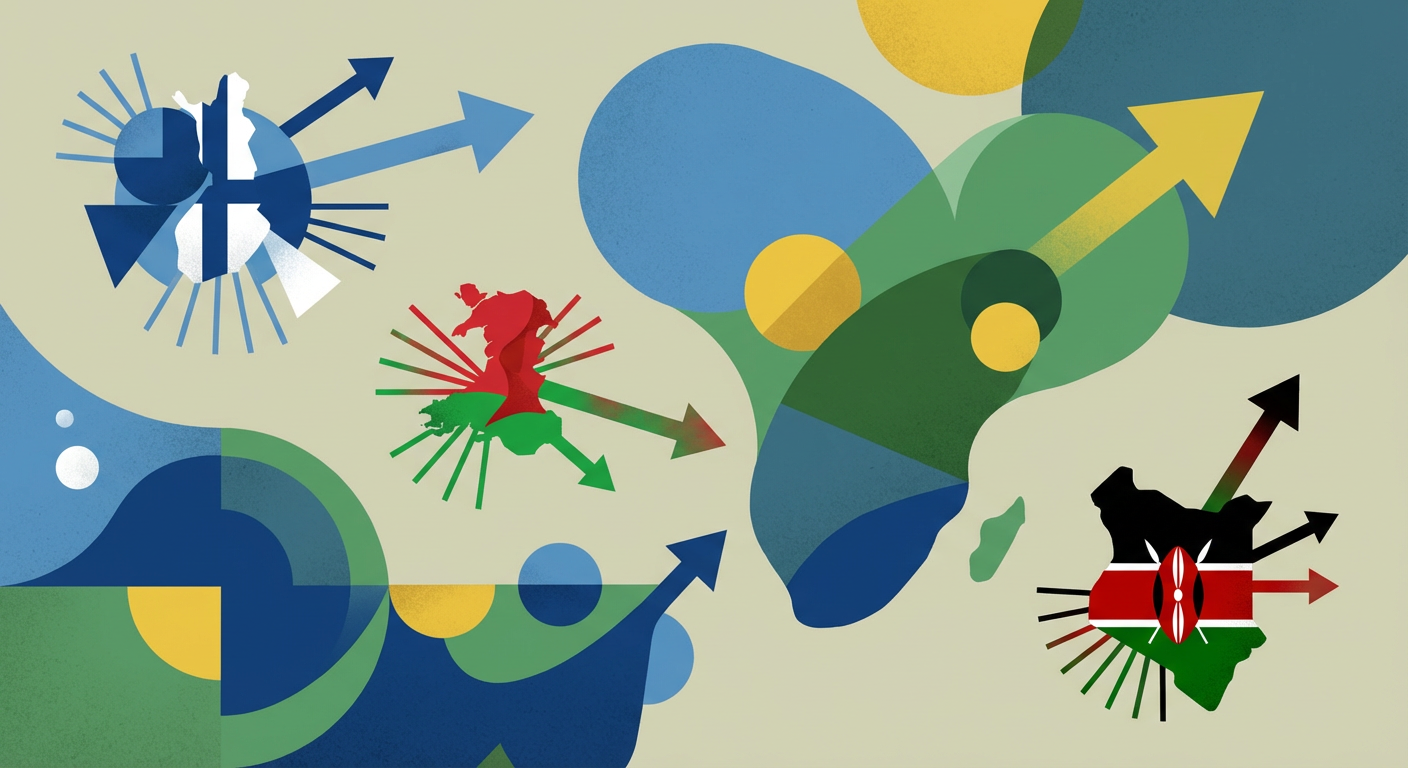
Governments at multiple levels are experimenting with policy responses that could reshape local economic conditions. Universal Basic Income pilot programs, following successful trials in Finland, Wales, and Kenya, now expand to more regions as policymakers test whether direct cash assistance can address inequality better than traditional welfare systems. These programs offer monthly payments to residents regardless of employment status, potentially providing the income security that gig work and housing costs have destroyed.
Wealth taxation proposals gain momentum in France and Spain, while several American states consider similar measures targeting high-net-worth residents. These initiatives aim to slow wealth concentration while funding public investments in education, infrastructure, and social services that benefit broader communities. Local implementation varies significantly, with some jurisdictions focusing on property tax reforms while others explore new revenue streams from capital gains or inheritance taxes.
The Brookings Institution research suggests that policy effectiveness depends largely on coordinated implementation across multiple government levels. Local zoning reforms can address housing supply constraints, but federal monetary policy influences mortgage rates and investment flows. State-level minimum wage increases can boost worker incomes, but immigration policy affects labor market competition. Regional cooperation becomes essential when addressing inequality drivers that cross city boundaries.
Generational Wealth and Future Prospects
Perhaps nowhere does economic inequality hit home more directly than in the growing importance of family wealth for young adults’ life prospects. Generational wealth transfer increasingly determines who can afford college without crushing debt, who can buy homes in their twenties, and who can take career risks like starting businesses or pursuing creative work. Families with built-up assets pass advantages to their children, while families without wealth watch their children face steeper barriers to middle-class stability.
This dynamic plays out differently across communities based on their historical wealth accumulation patterns. Neighborhoods that benefited from post-war suburban development and decades of property appreciation can transfer substantial assets to the next generation. Areas that experienced deindustrialization, discriminatory lending practices, or economic disruption often lack comparable wealth to pass down. The result amplifies existing regional inequalities while creating new barriers for talented individuals whose families can’t provide financial support during the career-building years that matter most.
Understanding how economic inequality shapes your community requires examining these interconnected forces rather than treating them as separate issues. Housing costs, employment patterns, policy responses, and generational wealth transfer create feedback loops that either lock in inequality or provide opportunities for broader prosperity. Getting involved locally with these challenges offers real ways for residents to influence outcomes that will determine their community’s economic future for decades to come.